



Ownership records, payments, and portfolios have largely moved to apps and online accounts. A balance can be viewed or transferred in seconds, and a digital record can make ownership easier to monitor. Yet speed and visibility do not determine what an asset is or why someone values it.
The persistence of physical holdings can therefore appear contradictory. Although records increasingly exist on screens, many assets remain objects that can be held, stored, moved, or inspected. Understanding this distinction requires separating the object itself from the records, rights, and prices attached to it. It also raises a broader question about which properties material ownership retains when access and record-keeping become digital.
What Counts as a Physical Asset
Before comparing physical and digital assets, the underlying definitions must be clear. In particular, an asset’s physical form, accounting classification, and stated value describe different qualities, even though those qualities can overlap.
Tangible, Intangible and Current Assets
A physical asset, also called a tangible asset, has material form and can be held, stored, moved, or inspected. By contrast, an intangible asset includes a trademark, licence, or software entitlement.
The value of an asset might mean its current market price, replacement cost, or balance-sheet figure, and those numbers rarely match.
Current assets are holdings expected to convert to cash within a year. They include cash, cash equivalents, marketable securities, accounts receivable, inventory, prepaid expenses, and short-term notes receivable. Physical and current assets are therefore overlapping classifications rather than competing ones.
Physical Assets You Can Actually Point To
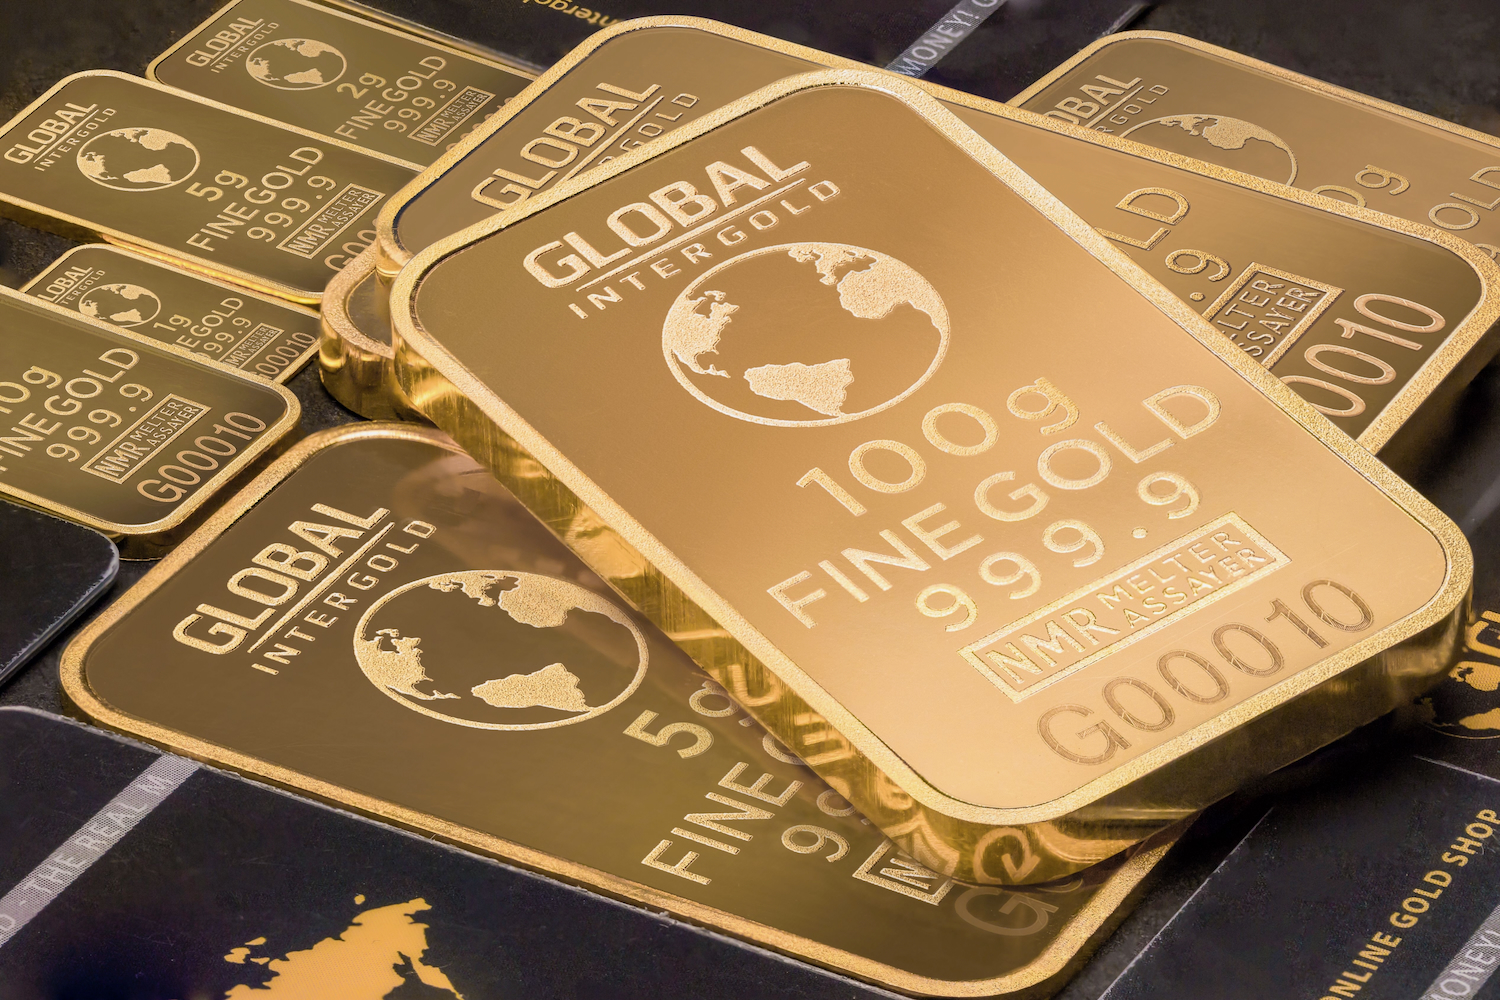
Physical holdings include real property, machinery, equipment, vehicles, inventory, precious metals, collectibles, deeds, documents, and keys. A warehouse of inventory, a delivery van, and an American Buffalo gold coin are all tangible, although their uses and valuation methods differ.
These categories show why physical form must be considered separately from liquidity, accounting treatment, and the digital records connected to an asset.
What Digital Convenience Does Not Replicate
Digital systems make assets easier to record, monitor, and transfer. However, they do not reproduce every property of direct possession. The distinction becomes clearer when custody, access, and verification are treated as separate mechanisms rather than as a debate about technology’s trustworthiness.
Custody, Counterparty Risk and Account Access
Direct custody places possession and control with the holder. No account suspension, platform insolvency, or service shutdown stands between that holder and the physical object. However, this also transfers responsibility for protecting valuable belongings to the owner.
Counterparty risk is the possibility that another party will not honour a claim. Digital assets held through an account depend on the institution maintaining the record and permitting access. An object held directly does not carry that same claim against someone else, although its authenticity and legal ownership can still be disputed.
Account-access failure is more ordinary than institutional collapse. Lost credentials, locked profiles, frozen transfers, and service outages can temporarily separate a holder from an otherwise valid digital record. Direct custody avoids those access failures but introduces theft, loss, and damage instead.
Verifying Something Without a Platform
A physical asset can be weighed, measured, inspected, and authenticated without network connectivity or a functioning service provider. Its dimensions, condition, serial number, or material composition remain observable even when associated records are unavailable.
Still, that independence does not make physical holdings safer overall. It gives them a different failure profile. Diversification across physical and digital assets can reduce dependence on any single custody, access, or authentication system rather than eliminate risk altogether.
How Value Is Measured on Each Side of the Line

Digital and publicly listed holdings usually receive a continuous market price. This makes asset valuation quick and visible, but the displayed figure reflects the market at that moment. It does not necessarily show what a thinly traded holding would realise in a large sale or what replacement would cost later.
Physical holdings commonly carry several values at once. An appraisal estimates likely market value from comparable sales. Replacement cost asks what acquiring an equivalent item would require, while book value records an accounting figure after depreciation. A delivery van might have a modest book value but a much higher replacement cost.
Material content introduces another layer. An American Buffalo gold coin, a .9999 fine issue with an iconic design, has measurable content alongside any premium for condition, rarity, or design. According to the U.S. Mint, each official bullion issue contains one ounce of .9999 fine, 24-karat gold.
Appraisal and authentication cost money and take time. Consequently, physical valuation is less frequent and precise than a screen price, but it is not less real. What matters is whether the quoted figure represents market value, replacement cost, intrinsic value, or book value.
The Costs and Friction of Holding Something Real
The argument for physical ownership only holds if its costs are stated plainly. Material independence brings expenses and operational demands that a database entry does not, while physical transfers usually require more effort than changing a name in a digital ledger.
Storage, Insurance and Slow Liquidity
Storage and insurance are recurring costs. Valuable objects need secure locations, while machinery, vehicles, and buildings require maintenance. Some holdings also incur transport, specialist handling, inspection, and environmental-control expenses.
Liquidity is often the sharper constraint. Converting an object into cash means finding a buyer, establishing condition, agreeing on a price, and completing physical delivery. A listed holding might trade within seconds, whereas a vehicle, collectible, or property can take days or longer to transfer.
Condition also affects the result. Wear and depreciation reduce equipment values, while uncertain provenance increases authentication expenses for collectibles and bullion. Documentation, maintenance records, and a clear chain of ownership therefore influence valuation and saleability.
Digital Records Managing Physical Holdings
In practice, physical and digital systems increasingly operate together. Digital inventories connect photographs, serial numbers, purchase records, appraisal histories, maintenance schedules, and insurance documents to the tangible assets they describe.
These records support maximising asset performance by making maintenance intervals, condition changes, and ownership information easier to track. They can also show when insurance values no longer match replacement costs or equipment has become more expensive to maintain than replace.
Technology has changed how physical assets are catalogued, priced, insured, and transferred without altering the distinction between the record and the object. A database can document a machine’s location and condition, but it cannot perform the machine’s work. Likewise, a digital inventory can track bullion or property without becoming the material holding.
Convenience Changed Access, Not Ownership
Digitisation improved how assets are recorded, monitored, and moved between parties, but that differs from replacing what is held. A physical asset still provides direct custody, independence from account access, and material verifiability. Digital assets provide faster transfers, easier tracking, and more visible pricing.
Each arrangement carries different costs and failure modes. Physical ownership requires storage, insurance, authentication, and patience with slower liquidity. Digital convenience introduces dependence on accounts, counterparties, and operational systems. The useful distinction is therefore not physical versus digital, but which risks a holder accepts and which forms of diversification reduce exposure to any one system.
